China’s Golden Week: Will Holiday Stats Offer Relief?
Investors brace for crucial economic data releases as China’s Golden Week holiday gets underway. Recent economic data have raised concerns about Beijing achieving its 5% GDP growth target for 2025.
Golden Week as a Key Economic Litmus Test
Golden Week typically serves as a barometer for the Chinese economy as Mainlanders celebrate the holidays. The government releases several key data sets on consumer activity that could dictate economic momentum through the fourth quarter.
What Traders Should Watch
Economists will analyze several key data sets, which will influence the fourth-quarter GDP. These include:
- Consumer spending: retail sales figures for major consumption categories, including dining, entertainment, and shopping.
- Payment and transaction data: transaction volumes reported by payment platforms.
- Tourism data: domestic tourist trips and overall tourism numbers, including travel trends.
- Transportation data: passenger volumes.
Beijing tends to highlight positive consumption trends as indicators of consumer confidence and economic robustness.
In 2024, spending during Golden Week contributed to 5% GDP growth, bolstered by policy measures, aimed at boosting consumption.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsNotably, retail sales rose 4.8% year-on-year in October 2024, up from 3.2% in September. Domestic trips increased 5.9% YoY, while tourism spending rose 6.3% YoY in October. Outbound travel surged 40% YoY on October 1, as overseas travel gained momentum after the effects of COVID-19 abated. Visa processing normalized, and flight capacity was restored.
Economic Pressures Challenge Consumption
Fast forward to 2025, and economists will closely scrutinize the year-on-year figures.
US tariffs on Chinese goods and transshipments have weakened external demand, intensifying competition. Rising competition has led to price wars and margin pressures. Firms responded to margin squeezes, cutting jobs to protect bottom lines.
China’s unemployment rate rose from 5.2% in July to 5.3% in August. Crucially, youth unemployment soared to 18.9%, up from 17.8% in July and 14.5% in June.
Rising unemployment and the ongoing housing crisis have weighed on consumer sentiment, challenging Beijing’s efforts to boost private consumption. Retail sales increased 3.4% year-on-year in August 2025, down from 3.7% in July and 4.8% in June.
Another set of weak consumption reports may raise doubts about Beijing achieving its 5% GDP growth target. However, policymakers could respond with further stimulus measures to revive the economy.
Stimulus Expectations Build
Goldman Sachs economists have raised the chances of the People’s Bank of China cutting interest rates to support the economy. While recent data have raised doubts, some economists warn Beijing may hesitate to add support if growth momentum appears sufficient to meet the 5% target.
Last week, lawmakers pledged further support, highlighting Beijing’s concerns about the economic outlook. CN Wire reported that policymakers will continue to strengthen and timely intensify implementation of macro policies and roll out measures promptly as conditions evolve.
According to CN Wire, China’s NDRC stated:
“China’s economy still faces significant risks and challenges amid tough and complex external environment. Will accelerate adoption of smart devices and systems across industries by introducing innovative consumer subsidies on the demand side. Will continue to enhance economic monitoring, forecasting, and early warning; prepare policy.”
Mainland Equity Markets: Rally at Risk?
Mainland equity markets have enjoyed three strong quarters of gains, despite the slowdown in Q3.
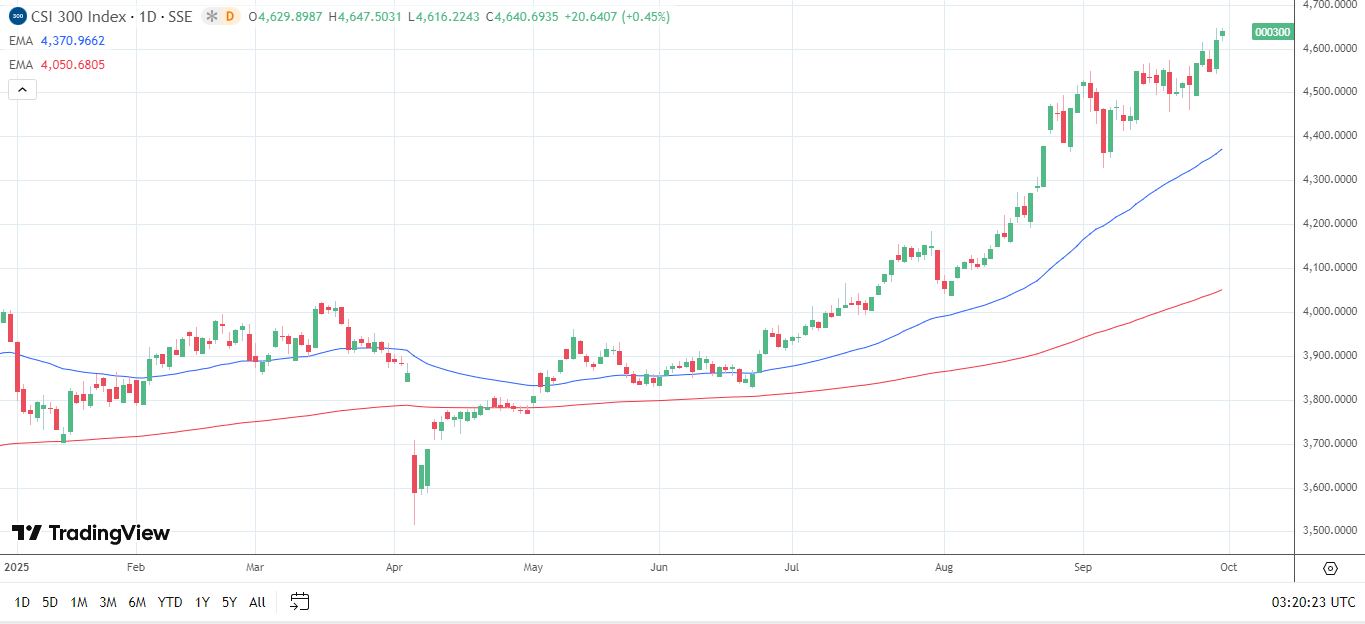
China’s advancements in the AI space, chip development, and expectations of further stimulus have lifted sentiment. The CSI 300 is up 17.94% year-to-date (YTD) and at a three-year high. Meanwhile, the Shanghai Composite Index has advanced 15.84%, climbing to a 10-year high.
Mainland-listed stocks remain below record highs, suggesting room for further gains if Golden Week data and stimulus support align. However, weak Golden Week data and the absence of fresh stimulus could weigh on sentiment.
For contrast, the Hang Seng Index has soared 36% YTD as the Hang Seng Tech Index surged 48.8%.
What’s Next? Trade Talks and Market Confidence
China’s Golden Week numbers will set the tone for the fourth quarter. However, trade developments will also influence sentiment, given the effect of tariffs on external demand and the labor market.
Easing US-China trade tensions and progress toward a trade agreement could drive demand for Mainland-listed stocks. Conversely, rising trade friction could weigh on sentiment. Hong Kong and Mainland equity market trends could be a focal point for Beijing.
Leading economist Hao Hong recently commented on the Mainland equity market rally and the potential effect on consumer sentiment, stating:
“There is no quick fix to boosting household confidence except for a stock market rebound. This is a topic that we economists have been discussing in the closed-door meetings in Beijing.”
Preserving market gains could prove crucial given the housing market woes and upward trend in unemployment.
Discover strategies to navigate this week’s market trends here.