Strong Bond Auction Steadies Equities
US stock benchmarks wrapped up Wednesday modestly lower after reclaiming earlier intraday losses, underpinned by a well-bid US$39 billion 10-year auction that pulled US Treasury yields back.
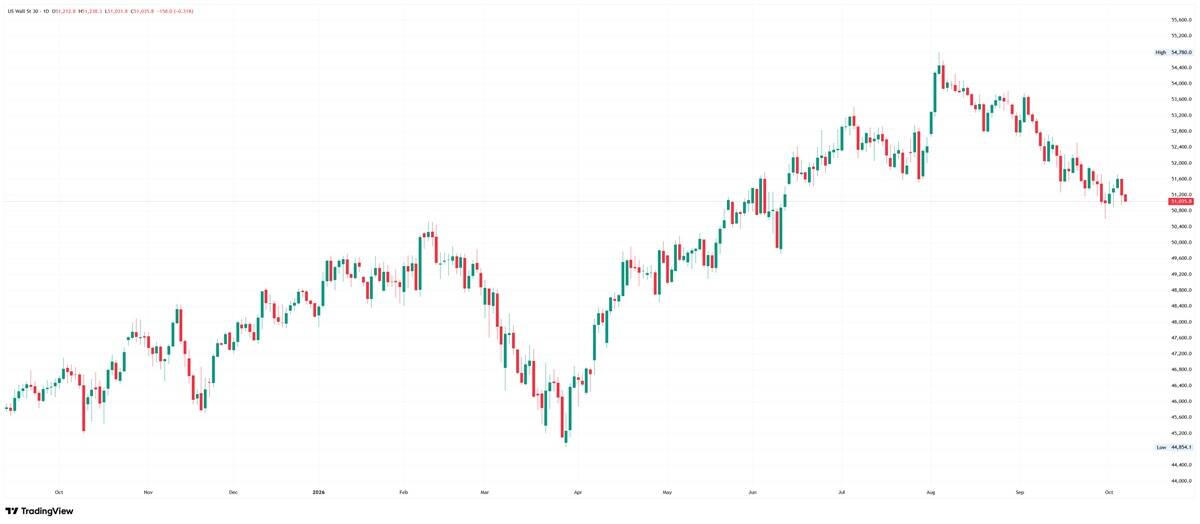
The Dow Jones fell 0.7%, the S&P 500 lost 0.2% – albeit still within a whisker of its 7,844 record – and the Nasdaq Composite lost 0.2%, while small caps bore the brunt of the losses, with the Russell 2000 falling 1.3%. US and European equity index futures are broadly flat right now.
Overnight in Asia, it is on track to be another red session. Japan’s Nikkei is down 0.7%, while South Korea’s KOSPI is off 1.1%. MSCI’s Asia-Pacific index excluding Japan has also given up about 1%.

Yields at Multi-Decade Highs & Euro Retests 17-month Low
For fixed income, longer-dated bond yields continue to trade at levels not seen in decades across many DM economies. In the US, 10s are around 5.3% – not seen since 2002. In the UK, the 30-year Gilt yield hit north of 6%, its highest since 1998, and we saw 4.92% on French 10s, with the OATs-Bund spread blowing out again to 140 bps. EUR/USD also slid to $1.1165 yesterday, retesting 17-month lows, with US$1.1112 considered the next support target.
For me, this is not just an inflation panic driving borrowing costs higher; breakeven rates are rising but still below their highs. Real yields appear to be doing the work, and they are currently circling 3%; this suggests investors expect robust growth. The issue is the rising term premium, which, if it continues to increase, could eventually hurt stocks. In other words, investors are asking for more compensation because they feel less sure about the long-term outlook.
Oil Climbs as Hormuz Traffic Thins
In the commodities complex, oil benchmarks are higher this morning, with WTI and Brent crude up about 1% – the latter is finding acceptance north of US$100/barrel. According to Kpler, vessel traffic through the Strait of Hormuz has fallen to a two-month low.
Fed Minutes
We also saw the minutes from the 15-16 September Fed meeting yesterday, which showed a unanimous rate rise, though for different reasons. Some officials viewed it as insurance against persistent inflation, while others wanted to prevent energy shocks from feeding into broader price pressures. Most, however, expect a further increase by year-end.
Dow Jones Price Forecast
Every new Dow Jones analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Dow Jones forecastsMarkets are now pricing in about a 19% chance of a move at this month’s meeting, but about 80% for December. Next Wednesday’s September US CPI release will be the key test.
Day Ahead
Fed Speakers
- Alberto Musalem (St. Louis Fed president) speaks on the US economy and monetary policy before Bloomberg’s ‘The Future of Fixed Income’ event in New York.
- Christopher Waller (Fed Governor) speaks on the economic outlook.
- Neel Kashkari is expected to join a conversation at the virtual 2026 Institute Research Conference, hosted by the Minneapolis Fed.
US Data
• Initial jobless claims (week ended 3 October): expected to rise by 3,000 to 200,000.
With the market pricing in about an 80% chance of a December hike, Fed speakers matter most. Musalem and Waller could shift expectations ahead of next week’s CPI.
Written by FP Markets Chief Market Analyst Aaron Hill