US Inflation Surprises Higher
My focus – and pretty much the entire market – was on the US September CPI inflation report yesterday at 12:30 pm GMT – the last inflation reading before this month’s Fed meeting.
MM, headline CPI was bang in line with consensus at 0.6%, up from 0.4% in August. Core held steady at 0.3%, though slightly hotter than the 0.2% expected. YY, headline picked up to 3.7%, topping the 3.6% forecast and 3.4% prior. Core also inched higher, reaching 2.6% versus expectations of 2.5% and a prior reading of 2.4%.
As expected, markets responded hawkishly: USD and yields rose, while stocks and gold took a hit. Notably, before the report hit the wires, the OIS market was pricing in about 7 bps of Fed tightening for the upcoming meeting (28% odds). By the close, the probability was much closer: around 50/50. The question is whether Fed Chairman Kevin Warsh and Co will hike a few days before the Midterms. Personally, I do not see a move this month, but at this point, a December Fed hike looks like a sealed deal.
S&P 500 Shaking Hands with 50-day SMA
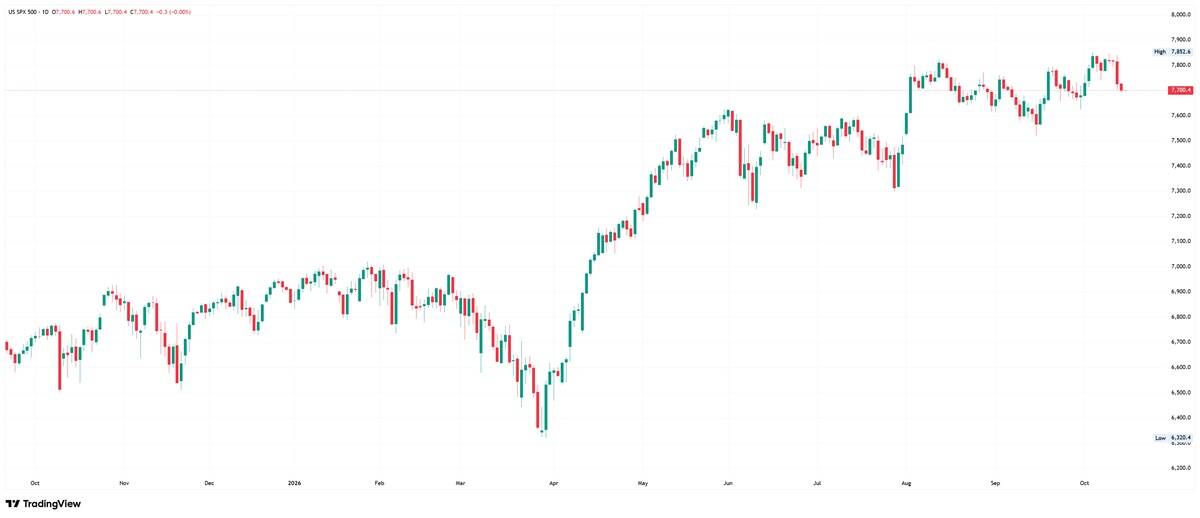
In equities, major US indices were red at the close yesterday, with the S&P 500 eking out a 1.1% loss and now touching gloves with its 50-day SMA around 7,707. Individually, BofA shed more than 8% at the open, weighed down by Q3 results that missed expectations, weak trading revenue, and a US$1.2 billion charge over money laundering and sanctions violations. The stock, however, clawed back a relatively large chunk of the losses throughout the session.
Brent Crude Eyes Resistance
For commodities, oil prices were relatively quiet yesterday, with Brent hovering around US$106/barrel; I am still closely watching US$108.40 as the next resistance level, with a break north clearing the runway to at least US$112ish. Gold, by contrast, fell on the latest inflation print but has since recovered most of the move.
FX: USD Bid; AUD Lower on Employment
In FX, the USD index refreshed YTD peaks just shy of 103 on revived Fed rate-hike bets, though upside momentum has certainly slowed this month. EUR/USD is within striking distance of monthly support at US$1.1112, which closely overlaps with the 50-month SMA at US$1.1031.
Overnight, the September Australian employment report landed, and it was largely disappointing. Employment fell by nearly 40k. Despite this, full-time employment rose by 34k; the overall fall came because part-time jobs fell by 73k, more than offsetting the full-time gain.
Gold Price Forecast
Every new Gold analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Gold forecastsUnemployment ticked higher to 4.7%, bettering the market’s maximum estimate of 4.6% (though it matched the upwardly revised 4.7% prior reading in August). The AUD fell on the report, but the move was short-lived, likely on the back of the full-time employment gain.
Day Ahead
August UK GDP numbers land at 6 am GMT, with MM expected to fall by 0.1%. Given how much tightening markets are pricing in for the BoE, a dovish print could jolt the GBP. Today’s macro focus then turns to the September US PPI inflation report. If it beats, it could prompt more hawkish Fed rate bets and underpin a USD bid.
Written by FP Markets Chief Market Analyst, Aaron Hill