Silver
Today, silver is entering the market with a somewhat easier financing backdrop, but an industrial-demand argument that still needs confirmation. Yesterday’s Treasury tables showed lower yields across key maturities. Today’s U.S. industrial production report, scheduled for 9:15 a.m. Eastern, can refresh the activity evidence as far as industrial demand is concerned.
The 2-year nominal Treasury par yield declined to 4.77% yesterday from 4.82% a day earlier. The 10-year nominal yield fell to 5.10% from 5.19%. The interpretation that I take away from this is that lower competing returns can ease one headwind for non-yielding investment positions and inventory financing for a market such as silver.
Real Yields
Real yields moved in the same direction. Treasury’s 10-year inflation-protected constant-maturity par yield declined from 2.84% to 2.70%. This is going to potentially improve the relative appeal of holding metal without contractual income. The relationship is conditional, though, because industrial activity, physical availability, and investment preferences will sometimes outweigh changes in financing costs.
PPI Shows Conflicting Info
Inflation remains an important opposing consideration. The September PPI report published on Thursday showed final-demand prices rising 1.3% monthly, seasonally adjusted, and 6.3% annually, unadjusted. Final-demand goods increased 2.6% monthly, services 0.8%, and energy 10.8%. The data are preliminary and describe prices, not the volume of goods produced or the amount of silver consumed.
The PPI measure excluding food and energy increased 0.7% monthly. Excluding trade services as well reduced that figure to 0.5%. The distinction prevents different definitions of underlying inflation from being confused in policy discussion.
This distinction matters for silver’s well-known dual role. A producer receiving higher selling prices may be experiencing healthy demand, constrained supply, or even higher costs. The possibilities have different implications for metal purchases. It would therefore be premature to call the PPI increase evidence of a surge in industrial silver demand, as higher prices can coexist with pressures on margins and purchasing power.
Silver Price Forecast
Every new Silver analysis as it publishes, today's technical signal and key levels, live price — on one page.
See all Silver forecastsFed Raised 25 Basis Points. Will They Raise More?
The latest available Federal Reserve production report is from September 18 and covers the month of August. Manufacturing output decreased 0.3% that month, while total industrial production was unchanged. The manufacturing index stood at 98.2, with 2017 equaling 100, compared with 98.4 in July. Today’s new release can test whether that setback continued. A stronger reading would improve the broader activity backdrop, but it would still not directly measure overall industrial silver orders.
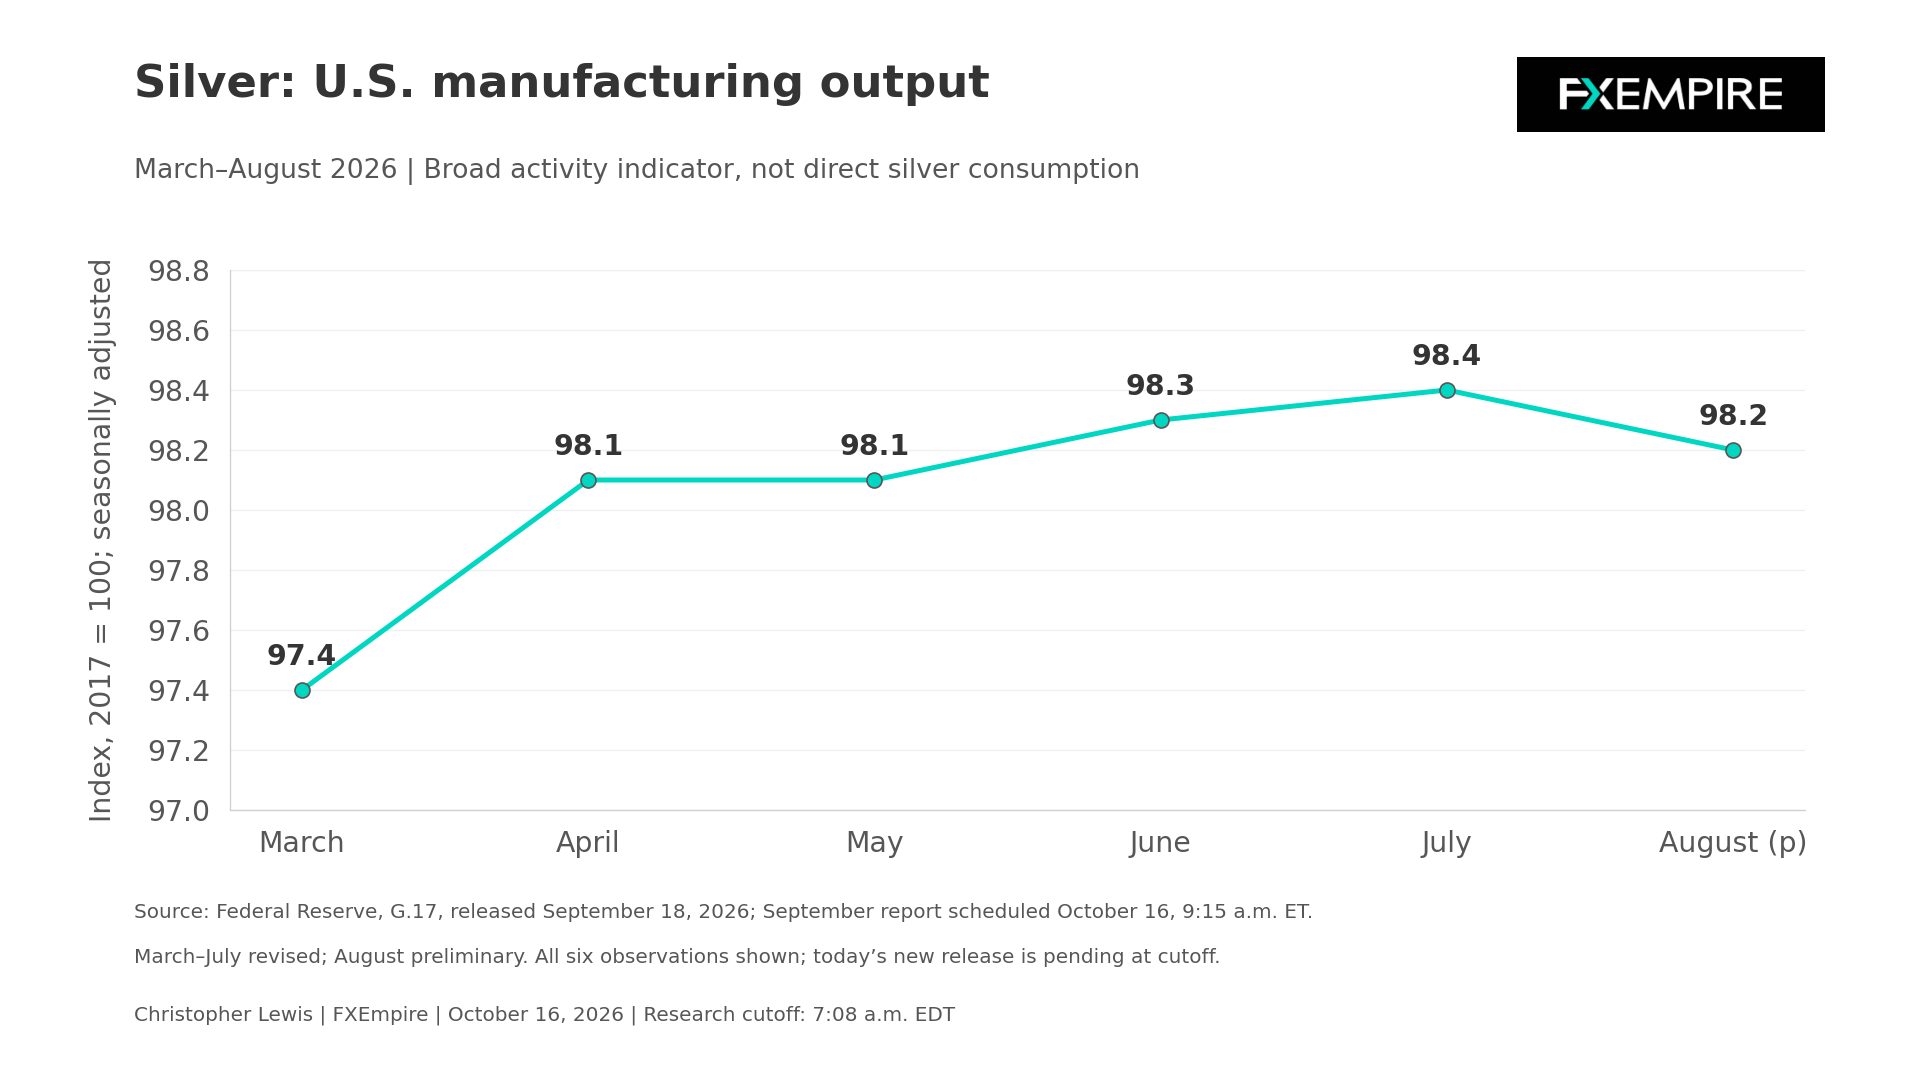
Silver’s electrical and electronic uses provide a structural reason to monitor manufacturing. USGS documents those applications and the metal’s conductivity. The background explains the relevance of industrial indicators. It does not establish that demand in every application is expanding today, though. One place you could see a claim about more demand could be solar-related consumption, but that remains unclear.
Yesterday’s PPI Report
Yesterday’s inflation information also needs to be distinguished from policy. The Federal Reserve’s latest decision on September 16 was to raise its interest rate 25 basis points to a target range of 3.75% to 4.00%. The next decision is still up in the air, but it does look as if the market believes the Federal Reserve is likely to hold.
The first scheduled data catalyst today is import and export prices at 8:30 a.m. in New York, and industrial production follows at 9:15 a.m. The former can inform the discussion of external price pressures. The latter provides a more direct test of output. Both will be monitored carefully.
In analytical terms, improving activity alongside stable or declining real yields would offer a more constructive combination, rather than either development by itself. Weaker activity and renewed yield increases would make things difficult for silver. The mixed result could leave it moving between its monetary characteristics and its industrial ones, making unsupported single-factor expectations unhelpful.
Silver Is Rallying Early on Friday
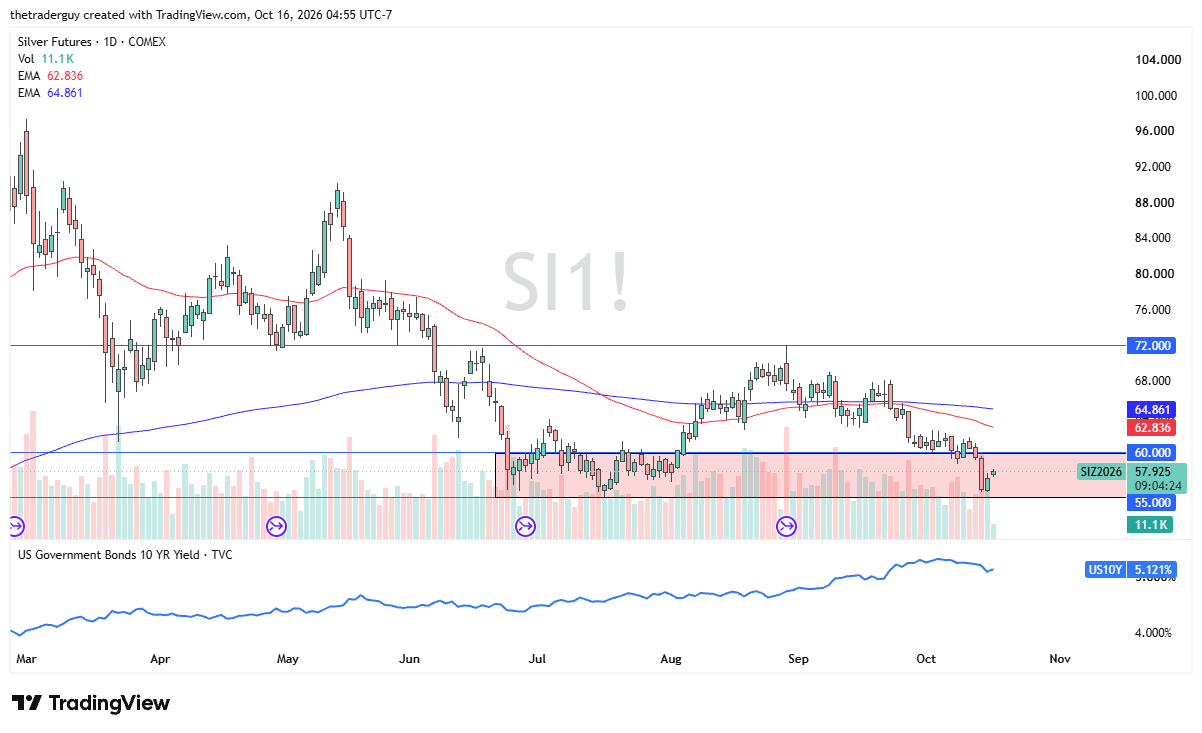
It looks like the continued bounce from the crucial $55 level is in play. There is a range between $55 and $60 that seems to be significant demand, and with yields dropping the way they have over the last couple of days, silver does have a little bit of a boost behind it at the moment.