Market Overview
U.S. equities finished the week mixed. The Dow Jones Industrial Average closed at 51,176.96, down 1.26%. The Nasdaq Composite settled at 27,190.86, up 0.45%, and the S&P 500 closed at 7,722.72, down 0.27%.
The 10-Year Treasury yield reached 5.34% Thursday before retreating after Friday’s weaker payrolls report. Higher energy costs, inflation concerns and heavy borrowing to fund AI expansion remain the main issues for long-dated bonds and equity valuations.
Third-quarter earnings begin to pick up with PepsiCo and Delta Air Lines. S&P 500 earnings are expected to rise more than 30% from a year earlier, while hyperscaler capital-spending plans remain the key AI question for technology traders.
The September FOMC minutes, services data, jobless claims and preliminary consumer sentiment lead the economic calendar. Oil-market headlines, the October Fed meeting and the November 3 midterm elections remain the bigger risks behind the data.
Key Economic Releases & Notable Earnings
Monday, October 5
Earnings Before the Open
No reports scheduled.
Economic Releases
13:45 GMT: Final Services PMI, forecast 58.7 (prior 58.7).
14:00 GMT: ISM Services PMI, forecast 55.1 (prior 55.4).
Earnings After the Close
No reports scheduled.
Tuesday, October 6
Earnings Before the Open
Apogee Enterprises (APOG), $0.63 per share;
Lamb Weston (LW), $0.59;
Neogen (NEOG), $0.05;
RPM (RPM), $1.95.
Economic Releases
ADP weekly employment changes for weeks ended September 19 and September 12, with a prior reading of 20.0K for the earlier week.
12:30 GMT: Trade Balance, forecast -$95.2 billion (prior -$88.6 billion).
RCM/TIPP Economic Optimism, forecast 44.5 (prior 45.6).
20:30 GMT: API Weekly Statistical Bulletin.
Earnings After the Close
Constellation Brands (STZ), $3.55 per share;
Penguin Solutions (PENG), $0.77;
Worthington Steel (WS), $0.92.
Wednesday, October 7
Earnings Before the Open
No reports scheduled.
Economic Releases
14:30 GMT: Crude Oil Inventories, prior 0.9 million barrels.
17:01 GMT: 10-Year Treasury Bond Auction, prior yield 4.83% and bid-to-cover ratio 2.7.
18:00 GMT: September FOMC Meeting Minutes.
19:00 GMT: Consumer Credit, forecast $15.4 billion (prior $18.1 billion).
Earnings After the Close
Applied Digital (APLD), loss of $0.30 per share; Levi Strauss (LEVI), $0.36.
Applied Digital is expected to report 94.0% year-over-year revenue growth to $124.57 million, though Wall Street expects a wider quarterly loss.
Thursday, October 8
Earnings Before the Open
PepsiCo (PEP), $2.30 per share; Helen of Troy (HELE), $0.50.
PepsiCo is expected to report revenue growth of 4.4% to $24.98 billion. Traders will watch for evidence that its North American food and beverage businesses are improving.
Economic Releases
12:30 GMT: Unemployment Claims, forecast 200K (prior 197K).
14:00 GMT: Final Wholesale Inventories, forecast 0.7% (prior 0.7%).
14:30 GMT: Natural Gas Storage, prior 64 Bcf.
17:01 GMT: 30-Year Treasury Bond Auction, prior yield 5.31% and bid-to-cover ratio 2.6.
Earnings After the Close
No reports scheduled.
Friday, October 9
Earnings Before the Open
Delta Air Lines (DAL), $1.94 per share.
Economic Releases
14:00 GMT: Preliminary University of Michigan Consumer Sentiment, forecast 47.6 (prior 48.1).
14:00 GMT: Preliminary University of Michigan Inflation Expectations, prior 4.6%.
Earnings After the Close
No reports scheduled.
Central Bank Activity
Tuesday, October 6, 14:45 GMT: Governor Michelle Bowman speaks.
Wednesday, October 7, 18:00 GMT: September FOMC meeting minutes.
Thursday, October 8, 17:40 GMT: St. Louis Fed President Alberto Musalem speaks.
Friday, October 9, 20:00 GMT: Boston Fed President Susan Collins speaks.
FedWatch showed an 83.9% chance of no October rate increase after Friday’s payrolls report, but the minutes and speakers can still move expectations for a December hike.
Technical Outlook
Weekly Dow Jones Industrial Average Index
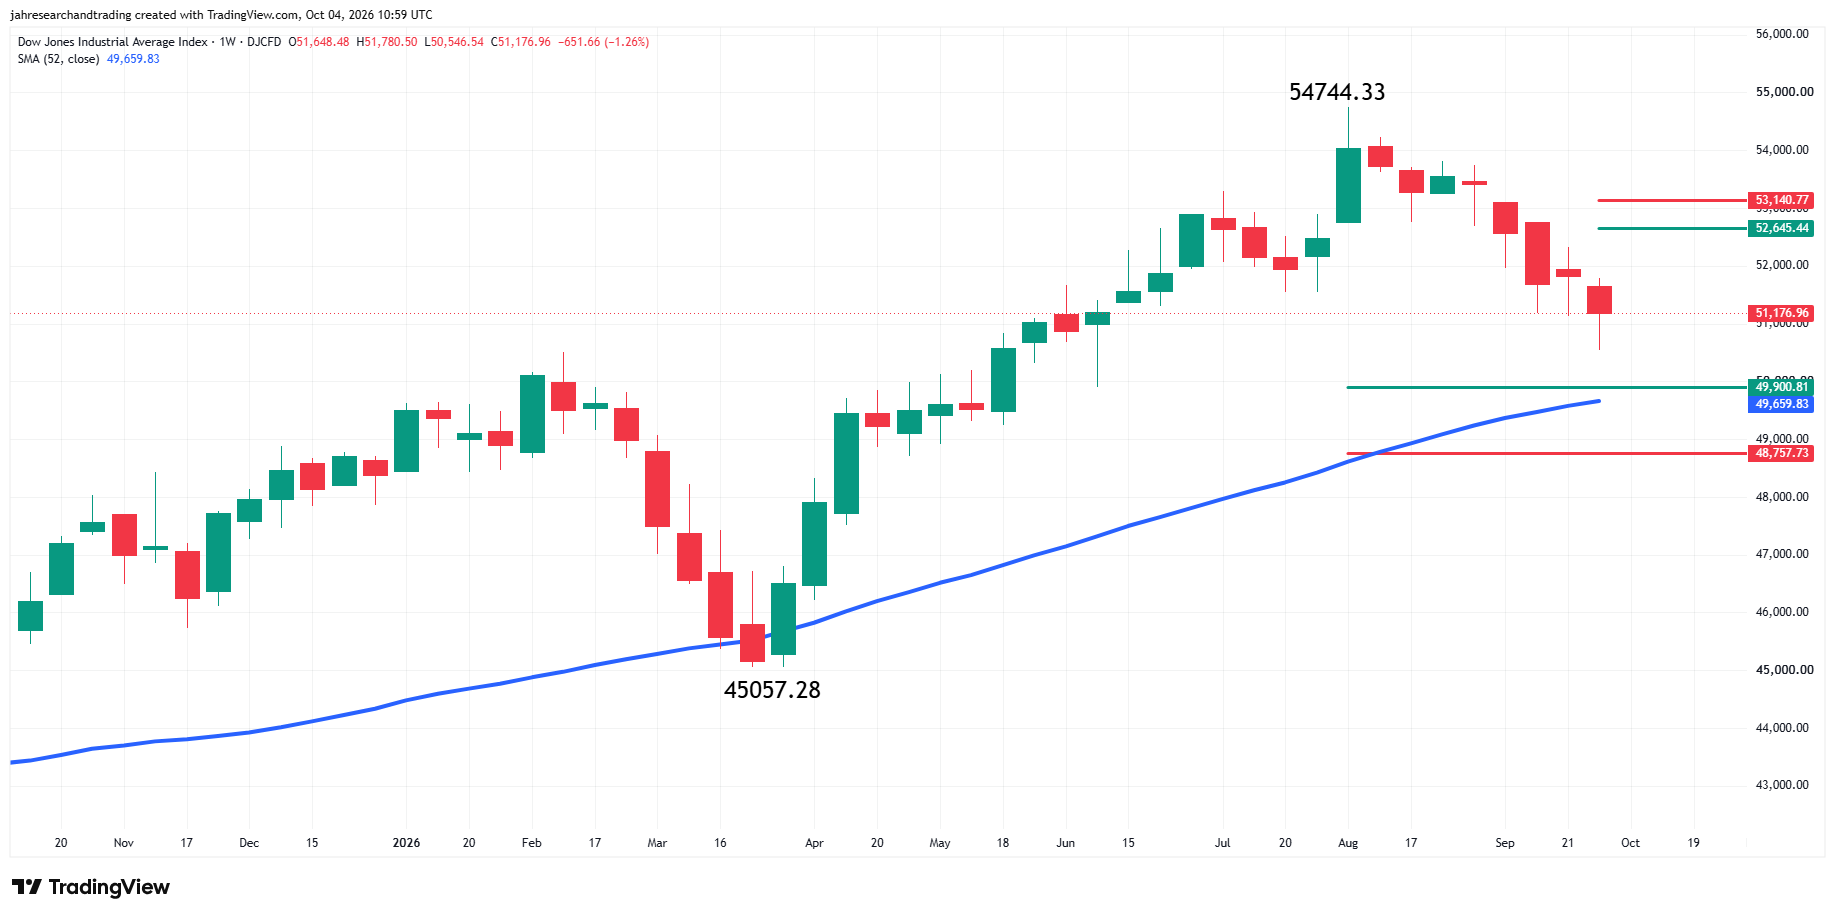
Dow Jones: 51,176.96 (-1.26%), Support at 49,900.81, the 52-week SMA at 49,659.83, 48,757.73 and 45,057.28, Resistance at 52,645.44, 53,140.77 and 54,744.33.
Weekly Nasdaq Composite Index
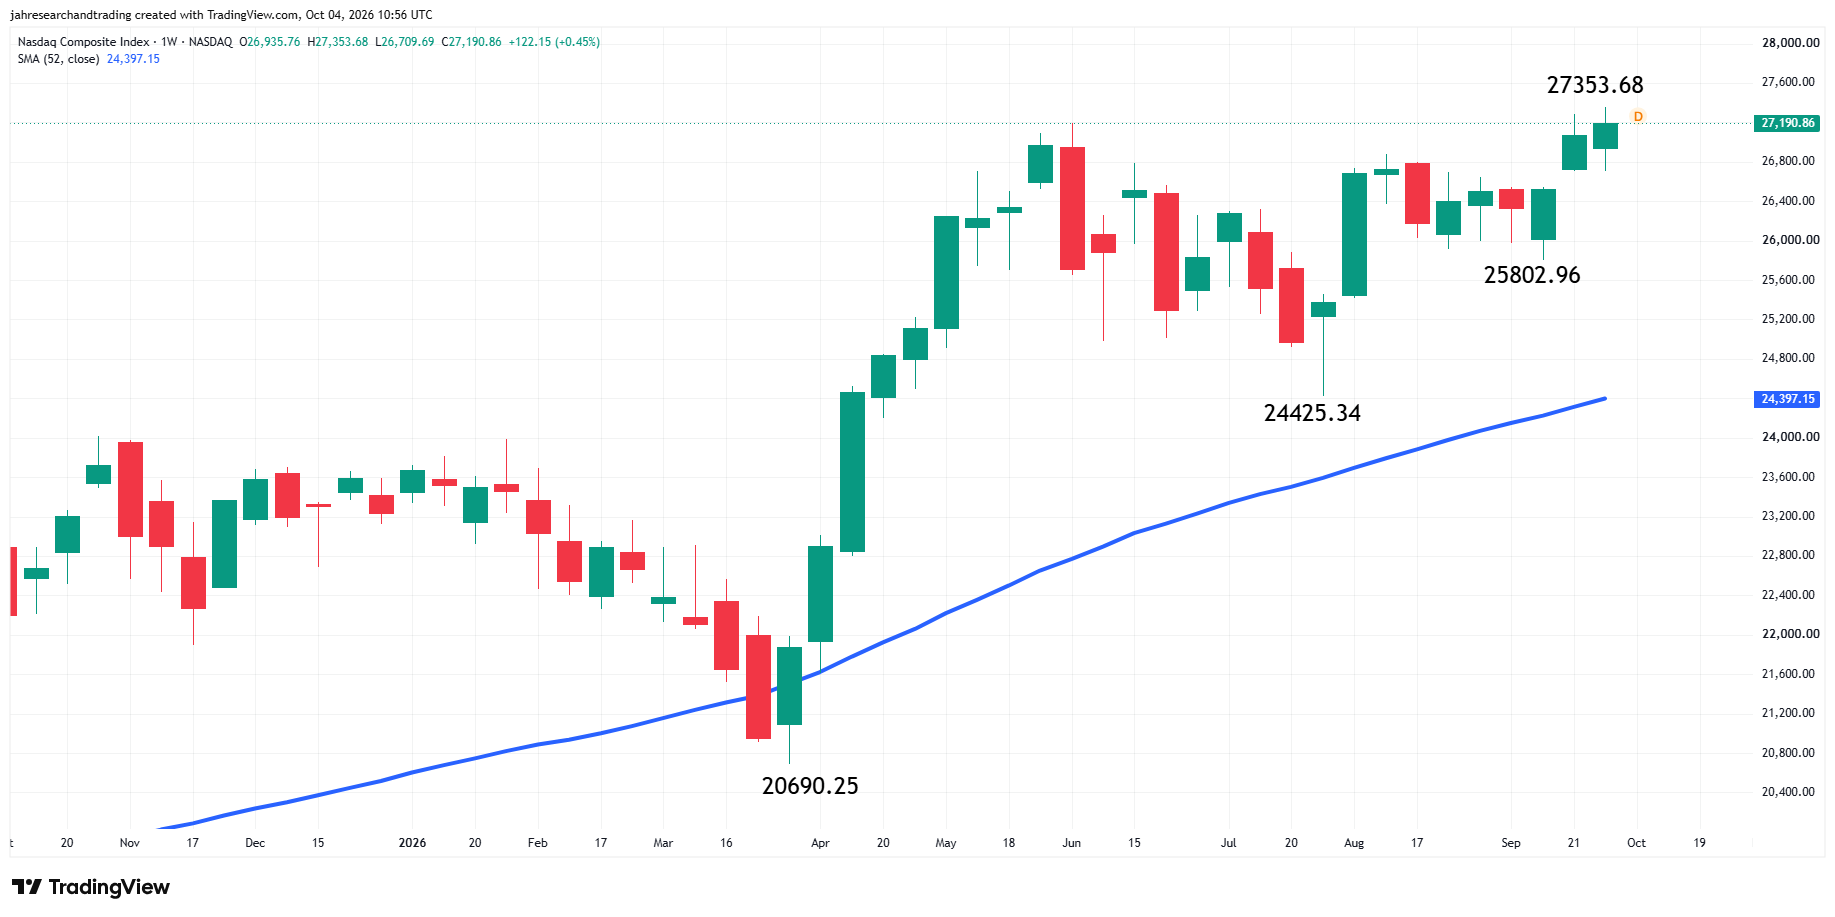
Nasdaq: 27,190.86 (+0.45%), Support at 25,802.96, 24,425.34, the 52-week SMA at 24,397.15 and 20,690.25, Resistance at 27,353.68.
Weekly S&P 500 Index
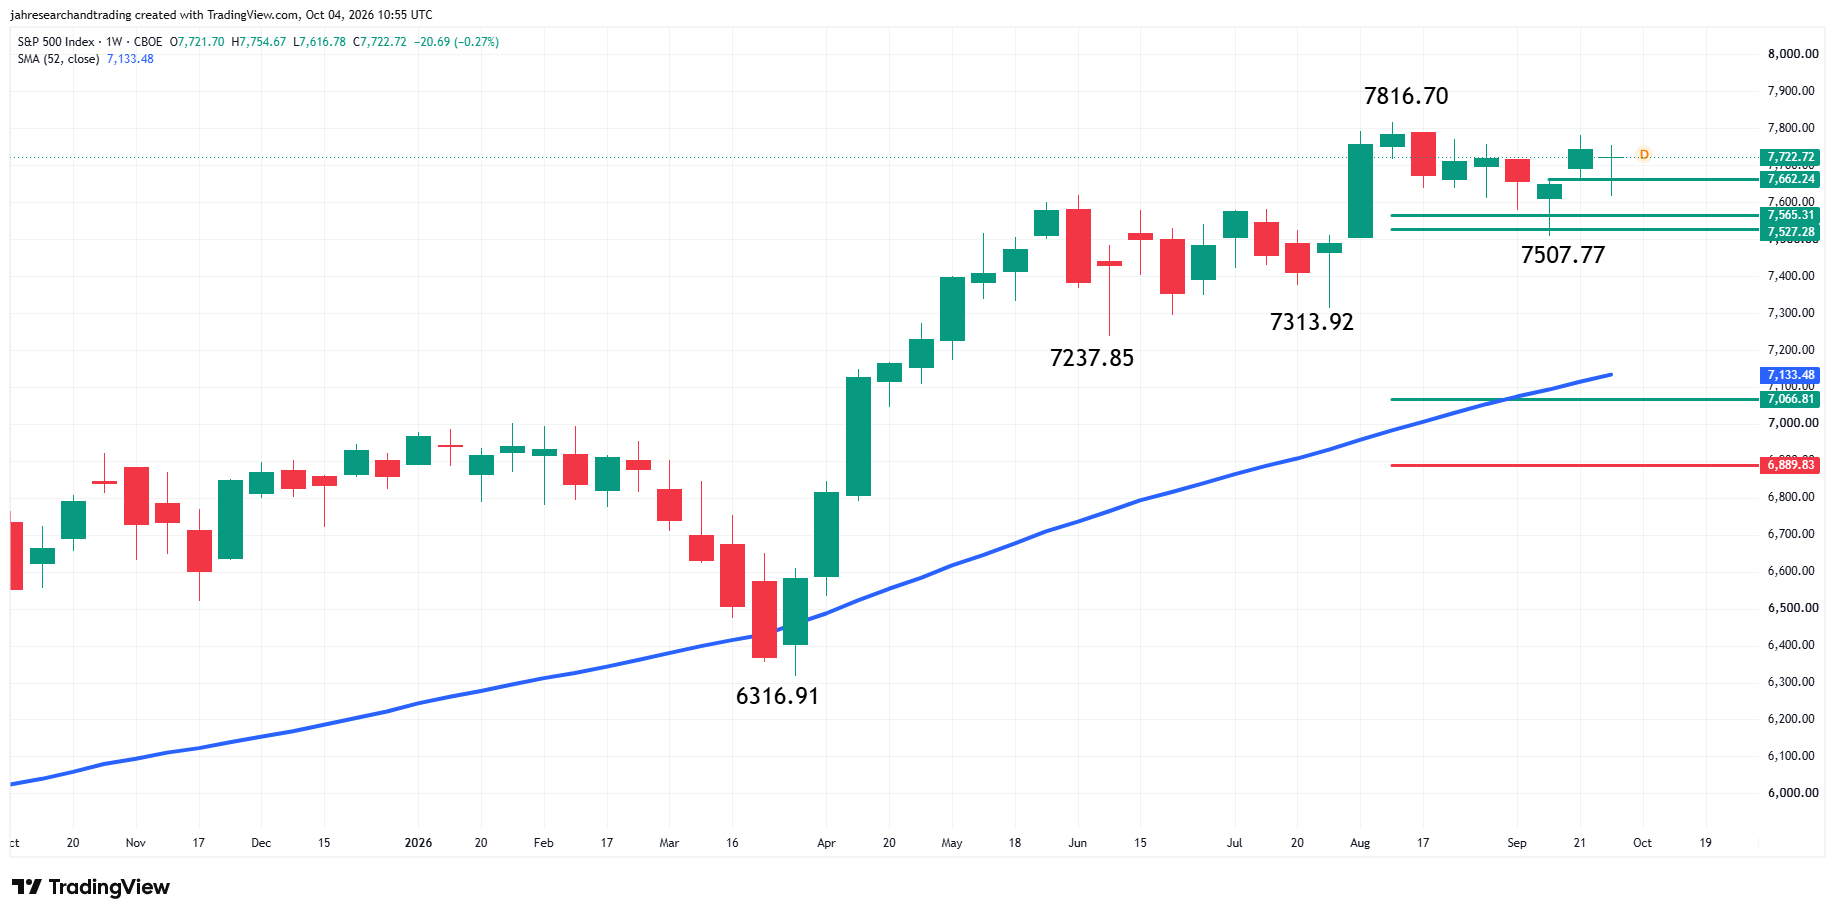
S&P: 7,722.72 (-0.27%), Support at 7,662.24, 7,565.31, 7,527.28, 7,507.77, 7,313.92, 7,237.85, the 52-week SMA at 7,133.48, Resistance at 7,816.70.
All major indices remain above rising 52-week SMAs, confirming an intact long-term uptrend.
Outlook
The September Fed minutes, Treasury auctions and October consumer-sentiment data are the immediate tests for yields. Traders will also watch whether OPEC+ action, Middle East headlines and European fuel-stock releases keep energy prices under pressure.
Seasonal strength and earnings growth support the fourth-quarter case, especially with the Nasdaq close to its record high. The rally remains vulnerable if long-term yields resume climbing, energy prices rebound or AI spending plans fail to meet the market’s high expectations.