


US CPI Inflation in Focus
Today’s macro slate focuses on the September US CPI report. Evidently, the backdrop has flipped entirely since we stepped into 2026, with markets pricing in rate cuts. Now, the OIS market is pricing in three rate hikes by mid-2027, with the Fed’s September SEP showing 16 of 18 officials project one more rate hike by year-end and 8 project another rate increase next year.
The September US payrolls and the August US PCE print came in broadly lower than expected. This, coupled with hawkish Fed rate pricing and bullish, crowded USD positioning (CFTC), suggests a miss could bring more volatility than a beat.
Per the forecast distribution, a beat would likely be the YY headline (core) coming in at or above 3.8% (2.6% or above), with MM at or above 0.7% (above 0.3%). For a miss, I will be looking for the YY headline (core) to come in below 3.5% (at or below 2.3%), with MM at or below 0.3% (below 0.2%).
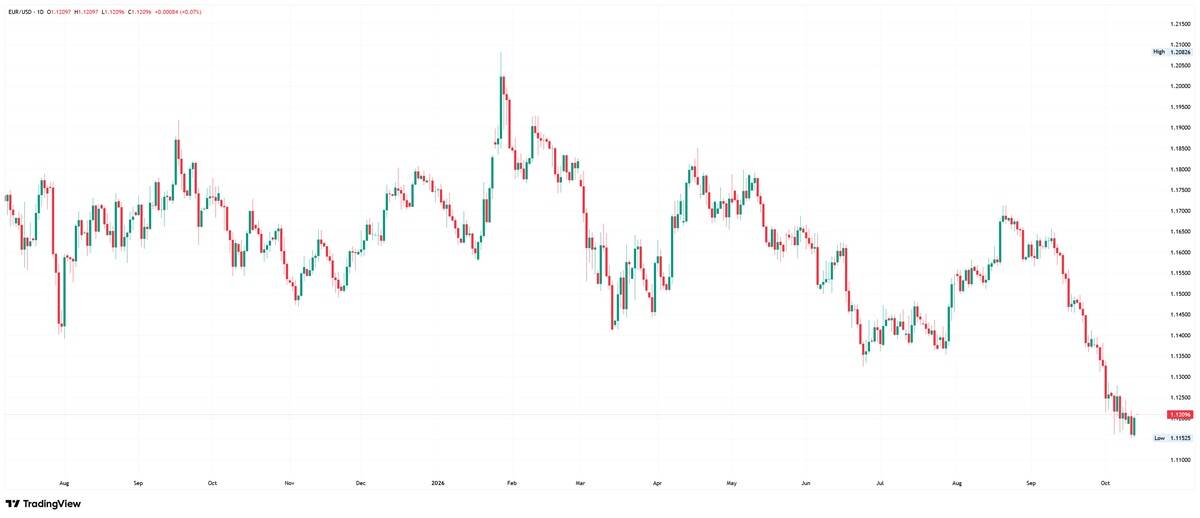
With USD longs crowded and EUR shorts stretched, a broadly soft print today could trigger an unwind and send EUR/USD higher. USD/JPY may also be a market of interest for shorts if there is a miss, due to intervention risks. A miss could unwind October Fed tightening bets, trim December hike odds, thereby weakening the USD and yields.
A hot print largely confirms current pricing, so I would expect a smaller reaction. On a strong beat, gold shorts might be in focus, as momentum is bearish while retail and large spec are long.
Bank Earnings: Goldman Stands Out
It was all about earnings yesterday. Goldman Sachs was the standout – beating on the top line and posting its second-highest quarterly net revenue. The company’s EPS came in at US$17.01, well above the US$13.09 market consensus, and revenue also beat at US$18.68 billion, versus the US$16.86 estimate. JPMorgan was more mixed, while Citi beat estimates, and Wells Fargo fell short on revenue.
JPMorgan and Wells Fargo disappointed, with JPM missing on EPS, revenue and fixed-income trading. Citi beat on EPS (US$2.85) and had its best third-quarter fixed-income result in at least a decade, yet its shares fell 5.6% – the worst day since April 2025, on conservative guidance.
Bank of America and Morgan Stanley report today.
Market Snapshot
In markets, US equity benchmarks ended yesterday largely unchanged, though they continued to circle all-time highs. FX shows the USD came under pressure yesterday, with the euro attempting to inch back above US$1.12 as I write.
New York Fed President John Williams recently hit the wires and said one more hike this year is appropriate and none in 2027, though he left the door open. US Treasury yields continued to pull back, with 10s testing 5.2% and 30s near 5.5%, while gold and oil prices ended slightly on the back foot yesterday.
Asia-Pac shares are under pressure overnight from AI-trade selling, with South Korea’s KOSPI unable to rally even after record Samsung earnings. Technically, the daily triple-top pattern’s downside objective continues to call for attention at 5,743.
Written by FP Markets Chief Market Analyst, Aaron Hill


